 Belgium
 Cyprus
 France
 Germany
 Guernsey
 Ireland
 Italy
 Netherlands
 Poland
 Portugal
 Spain
 Switzerland
 Turkey
 Australia
 China
 Hong Kong
 India
 Japan
 Malaysia
 New Zealand
 Philippines
 Singapore
 South Korea
 Thailand
 Vietnam
 Dubai
 Saudi Arabia
 Qatar
 Oman
 Kuwait
 Canada
 United States
 Brazil
 South Africa


Why a Decline Is Rarely the End of the Road
A decline letter can feel final. For expat mortgage applications, it almost never is. Most declines trace back to one specific thing – how the application was put together, not a blanket refusal to lend to expats as a group. Once you know what that thing was, a second application, often with a different lender entirely, tends to work.
Why Expat Mortgage Applications Get Declined
Income is the usual culprit – bonus or commission-heavy packages, contractor day-rate income, self-employed income paid in a currency the lender discounts. Beyond that: the country you live in sitting on a lender’s restricted list, a thin UK credit footprint, a property type the lender won’t touch (certain new-build flats, some leasehold terms), or a deposit source that wasn’t evidenced clearly enough to clear anti-money-laundering checks.
Speak to a specialist who works across the whole expat lending market, not one lender’s criteria.
Find Out Why Before You Do Anything Else
Decline letters rarely spell out the real reason. A broker can usually get the underwriter’s actual note by asking for it. Reapplying without that note means you’re working blind, and a wrong guess gets you a second decline on a credit file that didn’t need one.
How Long Should You Wait?
Depends what broke. A temporary affordability shortfall is worth giving a few months to resolve on its own. If the real problem was the wrong lender for your country of residence or income type, there’s often no reason to wait at all – resubmit to a better-suited lender straight away.
Fixing What Actually Got Flagged
Income structure the issue? A clearer breakdown, extra payslips, or an accountant’s certificate for self-employed or contractor earnings usually sorts it – see our expat mortgage application guide for exactly what evidence lenders expect. Country of residence the problem? Some lenders keep a shorter restricted list than others, and a broker can place the case somewhere that actually fits. Deposit source flagged? Get the paper trail showing the funds building up, or a gift letter where that applies, sorted before you resubmit – our guide to currency conversion and expat mortgages covers a common cause of deposit queries. Thin UK credit history? Some specialist lenders will accept overseas credit references instead.
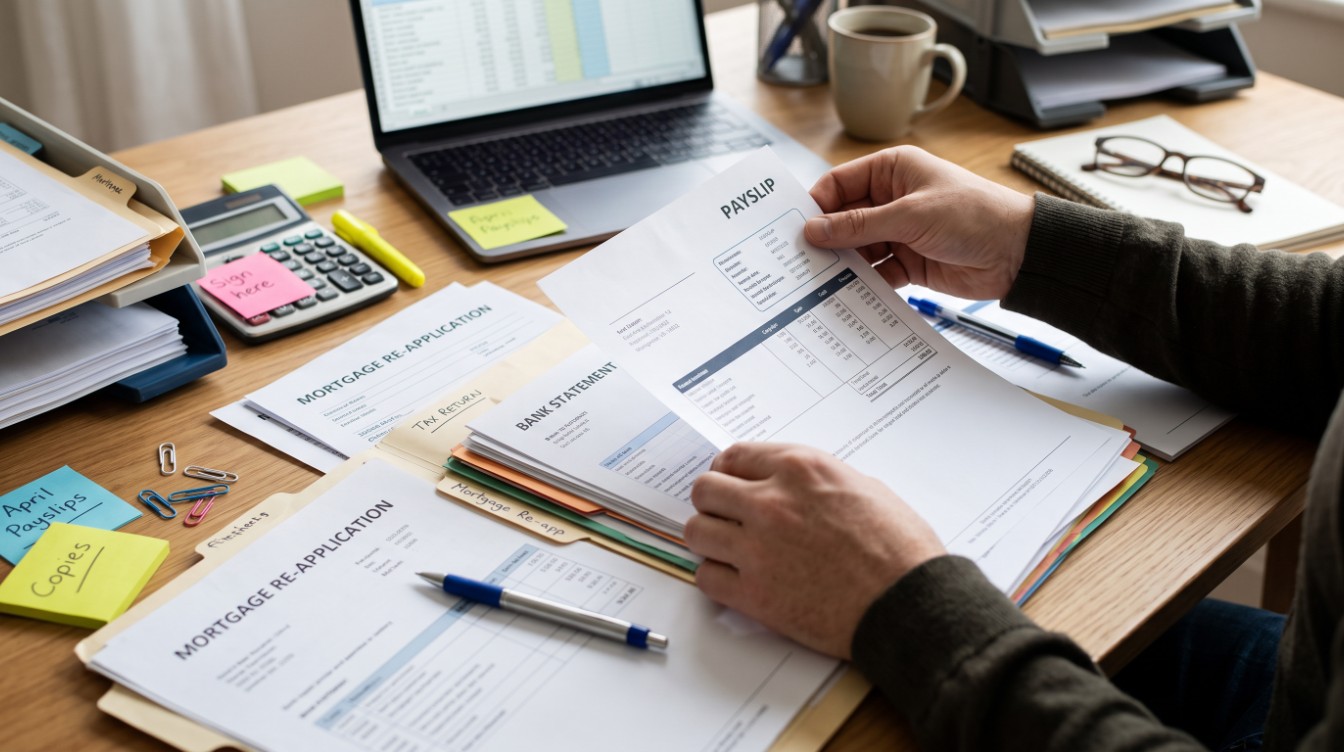
Getting the right evidence together before you resubmit makes the difference between a second decline and an approval.
When the Real Fix Is a Different Lender
Expat lending is a narrower market than mainstream mortgages, built around a smaller pool of specialist lenders. That’s exactly why a decline is so often about fit, not about the applicant – what one lender won’t touch, another whose lending criteria suit your income type or your country will often approve without you changing a single thing about the application. If the property itself is the sticking point, our buy-to-let mortgages for UK expats guide covers lender criteria specific to investment purchases.
Frequently Asked Questions
Why was my expat mortgage application declined?
Usually one specific thing. How your income was presented, your country of residence, or a deposit paper trail that wasn’t clear – rather than a blanket no to expats.
How do I find out the exact reason?
Ask your broker to request the underwriter’s actual decision note. It’s far more useful than the generic wording on a decline letter.
How long should I wait before reapplying?
Depends on the cause. A lender-fit issue can usually be resubmitted almost immediately, while a genuine affordability shortfall is usually worth a few months.
Can a different lender approve what one lender declined?
Yes. Expat lending is served by a narrower pool of specialist lenders than the mainstream market, each built around different income types, countries of residence and property types.
Will a decline show up on my credit file and hurt future applications?
A mortgage application usually triggers a visible credit search. One search on its own rarely has much impact; repeated applications to lenders who were never a fit is what actually adds up.
What should I prepare before reapplying?
Income evidence suited to how the new lender assesses it. Plus a clear deposit paper trail, and where relevant, an accountant’s certificate or an overseas credit reference.
Speak to a UK Expat Mortgage Specialist
Whatever country you’re applying from, and whatever sits behind the decline, we work across the whole specialist expat lending market, not one lender’s criteria. We’ve placed applications that were declined elsewhere with lenders whose criteria simply fit better – on income, residency or property type. Send us the decline details and we’ll tell you honestly whether a different lender is likely to say yes.
Expat Mortgages UK is a specialist broker directly authorised and regulated by the Financial Conduct Authority. We work exclusively with expats and foreign nationals buying UK property with overseas income. Your home may be repossessed if you do not keep up repayments on your mortgage.
Call us on +44 1494 622 555 or email info@expatmortgages-uk.com to speak to a specialist directly.
Related Pages
- Buy-to-Let Mortgages for UK Expats – if the declined application was for an investment property rather than a home.
- UK Expat Mortgage Application Guide – what to have ready before you apply, so the next submission is clean the first time.
- Understanding UK Mortgage Options for Expats – eligibility, LTV and how the application process actually works.
- Currency Conversion and Expat Mortgages – how FX timing can affect a deposit that gets questioned during underwriting.
- Expat Mortgage Case Studies – real examples of applications placed with a better-suited lender.